


Editorial Integrity
Making sound real estate investment decisions begins with reliable, data-driven insights. At Ziffy.ai, we offer an AI-native real estate investing, proprietary data-driven trend analysis, investment mortgage programs like DSCR loans, and a network of over 500 investor-friendly real estate agents to deliver the expertise needed for informed decisions. Our content is crafted by experienced real estate professionals and backed by real-time market data, ensuring you receive accurate and actionable information. Through a rigorous editorial process, we strive to empower your investment journey with trustworthy and up-to-date guidance.
Quick Answer: Can You Get a DSCR Loan in Nevada?
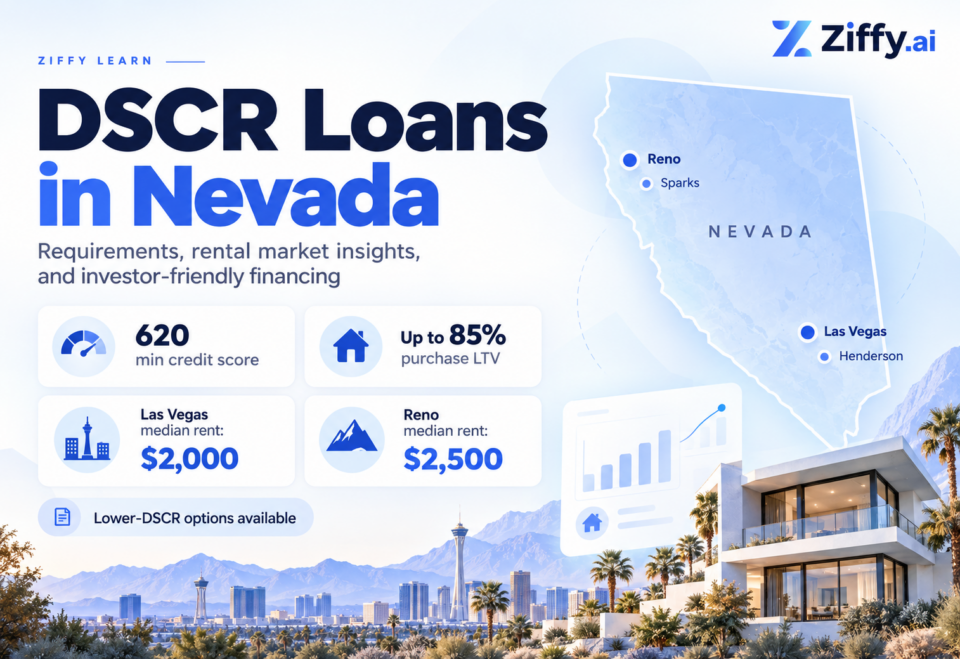
Yes. Ziffy Mortgage offers DSCR loans in Nevada for eligible investment properties in Las Vegas, Henderson, Reno, Sparks, North Las Vegas, and other communities.
Instead of qualifying primarily through personal employment income, investors can use the property’s qualifying rental income to support financing. Ziffy offers a minimum eligible credit score of 620, purchase financing up to 85% loan-to-value (LTV) in qualifying scenarios, and options for properties with a DSCR below 1.00.
Nevada investors should compare property-level rents, acquisition prices, insurance, taxes, HOA expenses, and local rental restrictions before choosing a financing structure.
Key Takeaways
Market source: Realtor.com, September 2026. Financing figures refer to eligible Ziffy programs and are subject to underwriting.
Table of Contents
How Does a DSCR Loan Work in Nevada?
A DSCR loan measures whether an investment property’s qualifying rental income can support its monthly housing payment. This can be useful for Nevada investors whose personal tax returns or employment income do not reflect their ability to purchase a rental property.
The lender calculates the Debt Service Coverage Ratio (DSCR) by dividing qualifying monthly rent by PITIA: principal, interest, property taxes, insurance, and applicable association dues.
Qualifying rent exceeds PITIA.
Qualifying rent equals PITIA.
Rent falls short of PITIA, but eligible lower-ratio programs may apply.
In Nevada, HOA charges deserve particular attention, especially in planned communities and condominium developments. Two homes with similar asking rents can have very different DSCR results if their recurring ownership costs differ.
DSCR is not the same as net operating cash flow. Vacancy, repairs, management fees, and capital expenditures may still affect an investor’s actual returns.
Investors can evaluate individual properties using Ziffy’s investment property research resources and the DSCR loan guide.
Nevada DSCR Loan Requirements: Credit Score, Down Payment, and LTV
Ziffy Mortgage offers DSCR financing for eligible non-owner-occupied residential investment properties across Nevada. The available loan structure depends on credit, rental income, property type, leverage, and other underwriting requirements.
| Requirement | Ziffy Mortgage DSCR Program |
|---|---|
| Minimum credit score | 620 |
| Preferred DSCR | 1.00 or higher |
| Below-1.00 DSCR | Eligible lower-ratio and No-Ratio options |
| Purchase LTV | Up to 85% in eligible scenarios |
| Rate-and-term refinance | Up to 80% LTV |
| Cash-out refinance | Up to 75% LTV |
| Loan amounts | $100,000 to $10 million, subject to program |
| Cash reserves | Starting at two months of PITIA |
| Loan options | 30-year fixed options |
| Qualifying income | Property rental income |
| Occupancy | Investment properties, not primary residences |
A minimum 15% down payment may be possible under the highest eligible purchase-LTV tier. Other scenarios require more equity. The borrower must still document identity, assets, property eligibility, and the rental income used in underwriting.
Eligible properties may include single-family rentals, townhomes, condos, and qualifying small multifamily buildings. Condominiums and properties with association restrictions require additional review.
Do not calculate your maximum purchase price from the loan-to-value limit alone. The property must also satisfy rent qualification, borrower eligibility, and other underwriting standards. The highest available LTV does not automatically apply to every investor or property.
Nevada Rental Market Comparison: Las Vegas vs. Henderson vs. Reno
Nevada’s rental markets do not follow a single pricing pattern. Southern Nevada offers a broad range of residential investment opportunities, while Reno and Sparks have different acquisition costs and rental benchmarks.
September 2026 asking-rent and home-listing data reveal the differences.
Median Monthly Asking Rent by Market
Selected Nevada markets | September 2026
Sources: Realtor.com Nevada and Clark County market data. Bars are proportional to the highest value shown. Asking-rent medians are not property-specific DSCR forecasts.
| Market | Median Listing Price | Median Asking Rent |
|---|---|---|
| Las Vegas | $465,000 | $2,000 |
| Henderson | $538,950 | $2,221 |
| North Las Vegas | $429,900 | $2,060 |
| Reno | $665,000 | $2,500 |
| Sparks | $629,000 | $2,645 |
Source: Realtor.com Research, September 2026 market snapshot.
Reno’s median asking rent was $500 higher than Las Vegas, but its median listing price was also $200,000 higher. These separate market medians should not be paired to calculate an investment yield. Investors need comparable purchase and rental data for the same property type, location, and condition.
DSCR Loans in Las Vegas: Which Neighborhoods Have Stronger Rental Benchmarks?
Las Vegas investors have more to compare than properties near the Strip. Summerlin West, Centennial Hills, Rhodes Ranch, Silverado Ranch, and Downtown Las Vegas show different combinations of asking rents and acquisition costs.
The September 2026 neighborhood data provide an initial screening tool. They do not establish which area offers the best cash flow.
Las Vegas Neighborhood Rental Heat Map
Median monthly asking rents | September 2026
Source: Realtor.com Las Vegas neighborhood data. Colors indicate asking-rent levels, not investment performance, appreciation, or expected DSCR. Citywide neighborhood medians may include different property sizes and types.
Summerlin West and Summerlin North
Summerlin West recorded a $2,950 median asking rent against an $827,500 median listing price. Summerlin North showed $2,230 in rent and a $510,000 listing median.
For investors, the distinction deserves closer study. Summerlin West’s higher rent may accompany substantially higher acquisition costs, while Summerlin North offers another pricing profile. HOA charges, community rules, and property-specific expenses can change the underwriting outcome.
Centennial Hills and Rhodes Ranch
Centennial Hills recorded a $2,100 median asking rent, while Rhodes Ranch recorded $2,200. Investors considering these communities should compare homes of similar size and condition and account for any association dues or leasing limitations.
Silverado Ranch and Southeast Las Vegas
Silverado Ranch’s $435,000 median listing price and $1,950 median asking rent make it worth including in a property-level comparison. Southeast Las Vegas had lower reported medians of $359,999 for listings and $1,600 for rent.
A lower purchase price may improve financing flexibility, but older property systems, repairs, or insurance expenses could offset part of that advantage.
Use this matrix to decide where to research individual properties. Then compare recent rents for matching homes, actual taxes, insurance quotes, HOA statements, property condition, and financing costs. A neighborhood with the highest asking rent does not automatically produce the strongest DSCR.
Henderson and North Las Vegas DSCR Loans: Where Should Investors Compare Properties?
Henderson and North Las Vegas sit within the same broader metropolitan region, but their purchase prices and rental profiles differ. For DSCR financing, the relevant question is how much qualifying rent an individual property can generate against its complete monthly payment.
Henderson Neighborhood Comparison
| Neighborhood | Median Listing Price | Median Asking Rent |
|---|---|---|
| Lake Las Vegas | $769,900 | $3,000 |
| Green Valley Ranch | $560,000 | $2,550 |
| Inspirada | $554,750 | $2,500 |
| Anthem | $649,000 | $2,395 |
| Cadence | $516,900 | $2,350 |
| Green Valley North | $469,900 | $2,076 |
| Green Valley South | $498,950 | $2,020 |
Source: Realtor.com Henderson neighborhood market data, September 2026.
Lake Las Vegas has one of the higher asking-rent benchmarks in this comparison, but its substantially higher acquisition price demands a careful payment analysis. Green Valley North and Green Valley South show lower price points, while Inspirada and Cadence warrant attention for investors comparing planned-community homes.
Association rules can be particularly consequential in these markets. Investors should review leasing restrictions, fees, and any applicable property-use limitations before relying on projected rental income.
North Las Vegas: Evaluate Purchase Price and Property Condition Together
In September 2026, North Las Vegas had a median listing price of $429,900 and a median asking rent of $2,060. Both figures were below or near the corresponding Las Vegas market medians.
Investors evaluating North Las Vegas rental properties should compare neighborhood-level lease evidence, property condition, HOA expenses, taxes, and insurance. The overall market median cannot establish the rent supported by a particular single-family home.
For both Henderson and North Las Vegas, DSCR qualification ultimately depends on the eligible property’s income and full monthly payment, rather than the city’s advertised median rent.
DSCR Loans in Reno and Sparks: How Do Northern Nevada ZIP Codes Compare?
Reno and Sparks deserve their own investment analysis. Property prices and asking rents vary substantially across northern Washoe County, and the cost of purchasing in a higher-rent neighborhood may outweigh the rent difference.
ZIP-level comparisons help investors narrow their research before evaluating actual rental comparables and financing.
Northern Nevada ZIP Code Rent Comparison
Median monthly asking rent, September 2026
Sources: Reno market data and Sparks market data. September 2026 ZIP-level asking-rent medians. Values describe available rental listings, not lender-approved rent or realized investment returns.
South Reno: Higher Rents and Higher Acquisition Costs
ZIP code 89511 recorded a $3,747 median asking rent and a $1,665,000 median listing price. The higher rent figure needs to be assessed against the purchase cost, property type, insurance, and any association dues.
North Reno and the North Valleys
ZIP code 89506 showed a $2,400 asking-rent median and a $489,700 median listing price. Compared with more expensive Reno ZIP codes, this gives investors a different acquisition-cost range to research, although comparable property condition and supported rents remain essential.
Sparks: Different Pricing Within the Same City
Sparks ZIP code 89436 showed a $2,825 median asking rent, while ZIP code 89431 showed $2,100. These differences make a citywide average insufficient for property underwriting.
For a Reno or Sparks DSCR loan, investors should compare current leases and rental appraisals with available neighborhood evidence and then calculate the complete PITIA. A high ZIP-level asking rent cannot substitute for the income of the property being financed.
Investment Properties on Sale in Nevada Today


How Do Nevada Property Taxes, Insurance, and HOA Fees Affect DSCR Loans?
A Nevada rental property can look affordable on its listing page and still struggle to meet a lender’s preferred DSCR. The difference often comes from the expenses included in the monthly housing payment.
Property Taxes
Nevada property taxes depend on the property’s taxable value, location, applicable tax rates, and assessment rules. Investors should verify the property’s current tax information and determine whether the existing tax bill is appropriate for estimating expenses after the purchase.
The Nevada Department of Taxation and the relevant county assessor or treasurer are useful starting points for tax research.
Insurance
Insurance premiums depend on the individual property and its coverage needs. Investors should obtain a quote for the intended rental use instead of assuming that an owner’s existing policy or an online estimate will apply.
HOA Fees and Rental Restrictions
Association dues are particularly relevant when comparing Nevada condos, townhomes, and houses in planned communities. Monthly assessments can reduce the DSCR, while leasing restrictions can affect whether the intended rental strategy is permitted at all.
- The current property tax statement and relevant assessment information.
- An insurance quote covering the proposed rental use.
- HOA dues, rules, and pending assessment information.
- Current leases or supported rental comparables.
- Property condition and anticipated repair expenses.
These documents help distinguish a property that qualifies for financing from one that can also meet the investor’s longer-term cash-flow objectives.
Can You Use a DSCR Loan for Airbnb or Short-Term Rentals in Nevada?
Potentially, yes. Eligible short-term rental properties may qualify for DSCR financing, but projected vacation-rental income cannot be treated as guaranteed qualifying income. Both the property’s legal operating status and the lender’s accepted rent documentation matter.
This is particularly relevant in Southern Nevada, where rental rules can change across municipal boundaries.
| Location | Important Regulatory Check |
|---|---|
| Unincorporated Clark County | County short-term rental licensing, eligibility, and location restrictions |
| City of Las Vegas | City-specific short-term rental and business licensing requirements |
| Henderson | Municipal short-term rental registration and operating requirements |
| North Las Vegas | Local authorization and property eligibility rules |
| Reno / Sparks / Washoe County | Applicable municipal or county rules for the exact parcel |
Clark County adopted its short-term rental ordinance in June 2022 under Nevada’s Assembly Bill 363 framework. The county explicitly distinguishes unincorporated areas from the incorporated cities of Las Vegas, Henderson, and North Las Vegas.
Investors should review the Clark County short-term rental requirements and verify the regulations for the property’s actual jurisdiction.
A Las Vegas mailing address does not necessarily mean the property falls under City of Las Vegas regulations. Some addresses are located in unincorporated Clark County. Confirm jurisdiction and legal rental eligibility before relying on nightly rental projections.
Even where short-term rental operation is permitted, the property must satisfy Ziffy’s applicable underwriting standards. Depending on the program, qualifying rent may require an approved appraisal, rental schedule, operating history, or other acceptable documentation.
Before purchasing, investors should calculate a long-term rental alternative as well. This gives them a clearer understanding of the property’s financing position if their intended short-term rental strategy is restricted or performs below expectations.
Can You Get a Nevada DSCR Loan With a Ratio Below 1.00?
Yes. Ziffy offers eligible below-1.00 and No-Ratio DSCR financing options. A property that does not fully cover PITIA with qualifying rent may still be considered, depending on credit, leverage, reserves, and other underwriting conditions.
This may be relevant when purchasing a higher-priced rental in Reno, a property with substantial HOA expenses in Henderson, or a Las Vegas investment where the intended financing produces a monthly payment above qualifying rent.
How Investors Can Improve a Low DSCR
Lower borrowing may reduce principal and interest, improving monthly debt coverage.
Use current leases and supported market comparables rather than an unsupported future rent estimate.
Confirm accurate taxes, insurance, and association dues before completing the calculation.
Evaluate whether an eligible program better fits the property’s income and the investor’s equity position.
A lower-ratio loan may offer a financing route, but it does not eliminate the investor’s responsibility to cover any operating shortfall. Investors should independently evaluate cash flow, vacancies, repairs, and long-term affordability.
Nevada DSCR Purchase, Refinance, and Cash-Out Loan Options
DSCR financing can serve investors at different stages of ownership. Ziffy Mortgage offers purchase and refinance options for qualifying Nevada investment properties.
Eligible purchase LTV, subject to property, borrower, and program requirements.
Refinance an eligible investment property under applicable program conditions.
Access eligible property equity while meeting applicable DSCR and underwriting requirements.
DSCR Loans for LLC-Owned Investment Properties
Investors may also explore qualifying ownership structures, including LLC ownership where permitted by the applicable program. Borrower documentation, guarantees, title requirements, and property eligibility must still be reviewed.
For investors purchasing multiple Nevada rental properties, the financing structure should account for property-level debt coverage and the borrower’s overall investment strategy.
What Should Nevada Investors Check Before Applying for a DSCR Loan?
The most useful DSCR analysis starts before an investor submits a loan application. Rental estimates, ownership costs, and intended property use should all be evaluated together.
“When I’m comparing two Nevada rental properties, I want to see the rent alongside the purchase price and every recurring housing expense. A property in Summerlin might command a higher rent than one in North Las Vegas, but that doesn’t necessarily mean the loan will have stronger debt coverage. The numbers have to work together. I’d rather identify a payment problem while we’re comparing properties than after the investor has committed to the purchase.”
“One of the first questions I’d ask about a Las Vegas short-term rental is whether the exact property can legally operate that way. You can have a great location and attractive projected nightly rates, but those projections aren’t enough if the property doesn’t meet local requirements. I’d also want to know what the home could rent for on a long-term basis. That gives us another way to evaluate the financing if the short-term rental income isn’t accepted under the program.”
“A DSCR below 1.00 doesn’t always end the financing conversation. I would look at how much equity the investor is contributing, what the property can reasonably support in rent, and whether a different loan structure makes sense. But I wouldn’t want someone choosing a lower-ratio loan without understanding the property’s ongoing cash requirements. Qualifying for the mortgage and being comfortable with the investment are two separate decisions.”
Nevada DSCR Loan FAQs
What credit score do I need for a DSCR loan in Nevada?
Ziffy Mortgage offers eligible Nevada DSCR loans with a minimum credit score of 620. Higher scores may provide access to different financing terms, depending on the loan and property.
How much down payment is required for a Nevada DSCR loan?
Eligible purchase scenarios may allow up to 85% loan-to-value (LTV), equivalent to a 15% down payment. Other scenarios require higher down payments. Final requirements depend on underwriting.
Can I get a DSCR loan in Las Vegas without W-2s?
Yes. DSCR financing generally does not require traditional W-2s or personal income tax returns to establish qualifying income. Investors must still provide documentation required for borrower, asset, and property underwriting.
Are DSCR loans available for Reno and Sparks investment properties?
Yes. Ziffy Mortgage offers eligible DSCR financing in Reno, Sparks, and other Nevada communities. Loan eligibility depends on the borrower, qualifying property income, and applicable underwriting requirements.
Can I qualify for a Nevada DSCR loan below 1.00?
Potentially. Ziffy offers eligible lower-ratio and No-Ratio loan programs. Credit score, down payment, cash reserves, and property characteristics determine whether a particular transaction qualifies.
Can I finance an Airbnb property in Las Vegas?
Potentially, if the property is legally eligible for the intended short-term rental use and meets the applicable DSCR program requirements. Investors should verify the exact jurisdiction, licensing rules, and acceptable qualifying income before purchasing.
Can an LLC obtain a DSCR loan in Nevada?
Eligible LLC ownership structures may be permitted, depending on the program. Entity documentation, guarantees, title, and underwriting requirements still apply.
What are Nevada DSCR loan interest rates?
Rates vary based on credit, DSCR, leverage, property type, loan structure, market pricing, and other factors. Investors should obtain a transaction-specific quote instead of relying on an advertised rate that may not apply to their property.
Can I cash-out refinance a Nevada rental property with a DSCR loan?
Yes. Ziffy Mortgage offers eligible DSCR cash-out refinancing up to 75% LTV. The final amount depends on the property’s value, existing debt, and underwriting requirements.
Which Nevada city is best for DSCR real estate investing?
No single city offers the best DSCR for every property. Las Vegas, Henderson, Reno, Sparks, and North Las Vegas have different listing prices, asking rents, and ownership costs. Investors should compare qualifying rent against actual PITIA and evaluate operating expenses before deciding.